The average Canadian business owner has $47,000 sitting in a corporate account earning 0.5%. Here’s why that’s a six-figure mistake.
Let me ask you something that might sting a little: How much cash is sitting in your corporate bank account right now? Not the working capital you need for next month’s payroll or your HST remittance. I’m talking about the retained earnings that have been piling up — the profit you didn’t pay yourself, the surplus you kept inside the corporation because you didn’t want to trigger a personal tax bill.
If that number is anything over $10,000, you’re bleeding wealth every single day that cash sits idle. And if it’s over $50,000? You’re costing yourself more than most people save in an entire year of RRSP contributions — without even realizing it.
Here’s the hard truth that nobody tells you: Your corporation’s retained earnings are a real estate machine waiting to be turned on. And the best part? You can deploy that cash into property without triggering the tax bomb that most business owners fear.
Let me show you how.
The Rot: What Idle Cash Is Costing You
When I sit down with business owners across Guelph and the GTA, the scene is almost always the same. They’ve built a profitable company — congratulations, that’s harder than anyone who hasn’t done it understands. But their retained earnings are sitting in a business savings account earning 0.5% to 1.5% interest. After corporate tax, after inflation at 3-4%, that money is shrinking in real terms every single day.
Let me put some real numbers on this. Say you have $100,000 in retained earnings earning 1% in a corporate savings account. After corporate tax at roughly 12.2% (the small business deduction rate in Ontario), you’re left with about 0.88% after-tax return. With inflation at 3%, you’re losing 2.12% of purchasing power every year. That’s $2,120 in real losses — on money you already worked hard to earn.
Now compare that to deploying that same $100,000 into a $500,000 rental property (using the other $400K from mortgage financing). If the property appreciates at just 3% annually and generates a 5% cap rate, your effective return on that $100K is over 15% — inside the corporation, tax-deferred until you sell.
The difference between “letting it rot” and “putting it to work” is roughly $15,000 a year on that $100K. Over five years, that’s $75,000. Over ten years, with compounding, it’s north of $200,000. That’s not a theory — that’s math.
Why Most Business Owners Never Pull the Trigger
I’ve met dozens of business owners who know they should invest their retained earnings. They’ve thought about real estate. They’ve talked to their accountant. And then… nothing happens. Why?
Three reasons, almost every time:
1. Fear of the shareholder loan. The minute you take money out of your corporation for a personal down payment, you trigger what’s called a shareholder loan — and potentially a taxable benefit. The CRA has very specific rules about this, and the penalties for getting it wrong can be brutal.
2. “My accountant said I can’t.” Many accountants are conservative by nature. They see the complexity and default to “don’t do it” rather than “here’s how to do it right.” That’s not a knock on accountants — it’s a systems problem. Most accountants are trained to minimize your tax bill, not to maximize your wealth-building strategy. Those are two different goals, and they sometimes conflict.
3. Analysis paralysis. Should you buy personally? Through the corporation? Through a holding company? With a partner? The options are overwhelming, so you do nothing. And doing nothing is the most expensive decision of all.
Let me walk you through the three main structures so you can see which one fits your situation.
Structure 1: Own It Directly Through Your Corporation
This is the simplest approach. Your operating corporation buys and holds the rental property directly. The rental income flows into the corporation, expenses flow out, and you manage it like any other business asset.
The good: Simple setup, low legal costs, no new corporation to register. Mortgage interest is deductible against rental income. You can use the corporation’s retained earnings as the down payment without triggering any personal tax (the money never leaves the corporate envelope). Capital gains on sale are taxed inside the corporation at the corporate rate (about 50% on the taxable portion), and the remaining funds go into your Capital Dividend Account — which lets you pay out tax-free dividends to yourself later.
The catch: The rental income is passive income for tax purposes. Once your corporation earns more than $50,000 of adjusted passive income in a year, you start losing access to the small business deduction on your active business income. That $50K threshold includes net rental income (rent minus expenses, plus taxable capital gains). If you’re already close to that limit, this structure could cost you more in lost SBD than it saves.
Who it’s for: Business owners with less than $50K in other passive income, who want a simple structure and don’t plan to scale past 1-2 properties inside the corp.
Structure 2: The Holding Company (Holdco) Strategy
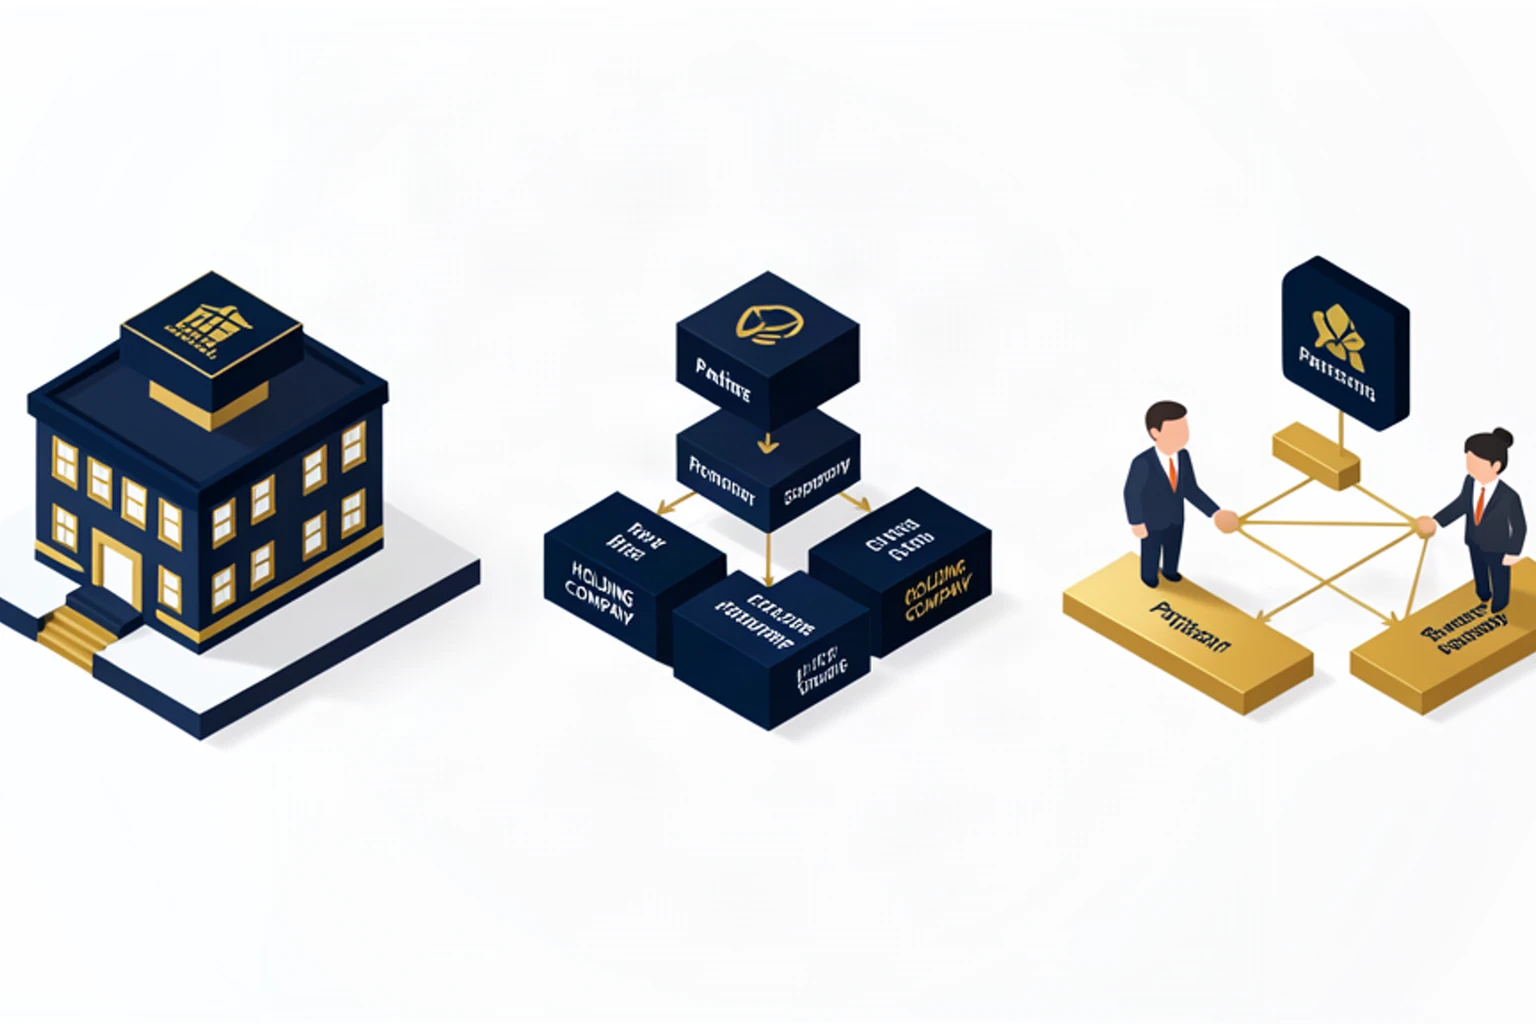
This is the structure I recommend to most established business owners. You set up a separate holding corporation (Holdco) that exists specifically to own and manage investment assets — real estate, securities, or both. Your operating company lends or dividend funds to the Holdco, and the Holdco buys the property.
The good: Because the Holdco is a separate legal entity, its passive income doesn’t count against your operating company’s $50K small business deduction limit. You can scale to multiple properties without triggering the SBD clawback. The Holdco can also hold your investment portfolio, your life insurance policies (corporate-owned), and other assets — it becomes a centralized wealth-building vehicle. When you eventually sell the operating company, the Holdco structure makes it cleaner to extract value without triggering a massive personal tax bill.
The catch: Setting up a Holdco costs money — typically $2,000-$5,000 in legal and accounting fees. You’ll need a corporate minute book, annual filings (T2 returns) for each corporation, and ongoing accounting costs. The inter-corporate dividend is generally tax-free under Section 112 of the Income Tax Act, but the legal structure needs to be set up correctly from the start. If you transfer an existing property into a Holdco after the fact, you can trigger deemed disposition and capital gains — so do this BEFORE you buy, not after.
Who it’s for: Business owners with more than $50K in passive income potential, who plan to own 2+ investment properties or a mix of assets. If your retained earnings are over $200K, this is likely your best path.
Structure 3: Personal Ownership with Corporate Financing
Here’s a lesser-known strategy that works well for many business owners: you personally own the property, but your corporation provides the down payment as a shareholder loan or inter-corporate dividend that flows to you personally.
The good: Rental income is taxed in your hands at your personal marginal rate — which might be lower than the corporate passive income rate. You keep the small business deduction intact in your corporation. Personal capital gains exemption (if applicable) could shelter some of your gain when you sell. You also build personal credit and mortgage history, which makes future financing easier.
The catch: The shareholder loan from your corporation to you personally needs to be documented properly with a signed loan agreement, interest at the CRA prescribed rate (currently 6% for Q4 2026), and a fixed repayment schedule. If the CRA recharacterizes it as a disguised dividend, you’ll owe tax at your full marginal rate plus penalties. This strategy requires disciplined documentation.
Who it’s for: Business owners who want to keep things clean, have personal tax room, and are comfortable with proper loan documentation. Great for a first investment property.
The 5 Methods: Where Real Estate Fits in Your Financial House
In the Financial House framework, real estate sits squarely in the Grow pillar — but it supports Protect and Earn too. The 5 Methods are your wealth-building tools: Real Estate, Insurance, Gold & Silver, Bitcoin, and Business. Each serves a different purpose.
Real estate is unique because it’s the only Method that simultaneously generates cash flow (Earn), appreciates in value (Grow), and can be leveraged — borrowed against — to acquire more assets. It’s also the Method that benefits most directly from corporate retained earnings, since you can deploy $50K-$200K of pre-tax corporate cash into an asset that controls $250K-$1M of property value through mortgage leverage.
If you already own a business, real estate is your natural “second engine.” Your business generates the cash; your real estate portfolio stores and grows it. The two work together better than almost any other combination I’ve seen.
The One Thing Nobody Tells You
Here’s the part that most advisors won’t tell you because it sounds counterintuitive: Sometimes the best tax strategy is to pay more tax today.
Let me explain. If you keep $100K inside your corporation earning 1%, you pay roughly $122 in corporate tax and call it a day. But your real return is negative after inflation. You’ve successfully avoided tax — and lost wealth in the process.
If you instead deploy that $100K into a rental property, you’ll trigger some tax along the way — maybe a bit of rental income tax, some capital gains down the road. But you’ll also build real, tangible wealth that grows faster than inflation. The tax you pay is a cost of doing business, not a penalty. It’s the price of admission to a much bigger outcome.
The destroyer here is inaction — one of the 7 Destroyers of Wealth that I see more than almost any other. Not the obvious ones like debt or taxes, but the quiet destroyer: the comfort of “I’ll figure it out next year.” Next year turns into five years. Five years turns into your retirement — except you never actually retired, because your corporate retained earnings (which could have been a real estate portfolio) are still sitting in a savings account.
Your Next Move
If you have retained earnings sitting in your corporation and you’re ready to stop the rot, here’s what to do this week:
Step 1: Check your corporate bank balance. How much is truly surplus — beyond what you need for 3-6 months of operating expenses, HST, and payroll?
Step 2: Have a conversation with your accountant — not about “should I?” but about “how should I structure this?” Bring them the three options above and ask which one fits your situation.
Step 3: If your accountant hesitates, that’s your signal to bring in a second opinion from someone who specializes in corporate real estate strategies. A good corporate-tax-focused CPA is worth their weight in gold here.
Step 4: Pull the trigger. The perfect structure doesn’t exist. The best structure is the one you actually execute.
Your retained earnings are one of the most powerful wealth-building tools you have — but only if you deploy them. Money sitting still is not wealth. It’s potential that hasn’t been unlocked yet.
Not sure where you stand? Take the 2-minute Financial House Assessment and get your personalized report — free.
Want to go deeper? Check out Essentials of Money ($50), The Wake Up Call ($50), or book a free discovery call.